I'm Agu Ukaogo. I moved to Los Angeles in 2012, buried my mother a few months later, and rebuilt my entire life in that city before rebuilding it again here in South Florida. So when a California client tells me they love the place but the math stopped working, I don't argue and I don't oversell. I've lived both sides of this move. I give you the real numbers, an honest read on the condo market, and a plan to protect what you've built on the way out.
I get a version of this call every week. Someone in Santa Monica, Palo Alto, or the Bay Area who just ran their tax return, just got a quote on homeowners insurance, or just watched a neighbor list and leave. They're not angry at California. They're doing arithmetic.
And the arithmetic is not subtle. The most recent American Community Survey estimates show 36,194 Californians moved to Florida in a single year, against 15,988 Floridians going the other way. That's a net gain of roughly 20,200 people for this state from California alone. Among Californians researching a move right now, Florida ranks second only to Texas. This isn't a headline trend that already peaked. It's a steady flow, which is precisely why it hasn't fully priced into the Miami condo market yet.
Why California Residents Are Moving to Miami
Let me be direct, because I'm not here to trash a state I loved living in. California gave me a decade of my life. This move isn't about California being bad. It's about what you keep and what you build.
- 13.3% versus zero. California's top marginal income tax rate is the highest in the country. Florida is one of seven states with no personal income tax at all. For a high earner, that isn't a line item. It's a second mortgage payment you're making to Sacramento every year.
- Capital gains are taxed as ordinary income in California. This is the one that moves people. Vested equity, a business sale, appreciated real estate — California takes its cut at your ordinary rate. Florida takes nothing. I have watched a single liquidity event justify an entire relocation, and the clients who timed it right are the ones who talked to a CPA before they signed anything.
- No estate or gift tax here. Florida doesn't touch what you pass down. If legacy is part of your thinking — and if you've read this far, it is — that's a generational difference, not a rounding error.
- What your housing dollar actually buys. California buyers are routinely stunned by what a Miami condo costs per square foot compared to coastal California, especially in the new and newer towers. You're often trading an older, smaller unit for a newer, larger one with an ocean or skyline view.
- Your industry is already here. Companies keep moving headquarters to South Florida — Palantir out of Denver, D‑Wave Quantum choosing Boca Raton over Palo Alto, Citadel in Miami, Wells Fargo moving wealth operations to West Palm Beach. Brickell asking rents now run above Manhattan's. You're not leaving your career. You're moving it somewhere it costs less to have.
Californians tend to think of the tax hit annually. Run it over a decade instead. A household paying roughly $45,000 a year in California state income tax is handing over about $450,000 in ten years — before a single equity event. A $5 million liquidity moment at California's top rate is roughly $665,000 in state tax, and $0 here. On a Miami condo in the $900K–$1.5M range, the tax you stop paying can carry a meaningful share of the purchase. Your exact numbers depend on income, deductions, and filing status — get a CPA to run them.
California vs. Miami: What Actually Changes
| Category | California | Miami / South Florida | Difference |
|---|---|---|---|
| State Income Tax | Up to 13.3% top marginal | 0% | Highest spread in the country |
| Capital Gains Tax | Taxed as ordinary income | 0% | Decisive for equity holders |
| Estate Tax | None, but income tax applies | None | Cleaner for legacy |
| Condo Market | Tight coastal supply | 14+ months supply | Buyer leverage here |
| Days to Contract | Varies, often fast | ~71 days for condos | Time to do due diligence |
| Natural Risk | Fire, quake, insurance pullback | Hurricane season | Different risk, not no risk |
| Corporate Momentum | Losing HQs | Gaining HQs | Demand tailwind |
I'll name the tradeoff honestly, because I don't sell fantasies: you're trading dry heat for humidity, mountains and canyons for water, and wildfire and earthquake exposure for hurricane season. What you're not trading away is quality of life. And every piece of the financial math is running in Miami's favor right now.
Where California Transplants Should Actually Look
California buyers sort by lifestyle the same way we do — you know that Venice, Pasadena, and Newport are three different lives. South Florida is the same. It is not one market. It's a dozen distinct communities, and picking wrong costs you more than overpaying by a little.
Brickell
The financial and tech core — vertical, walkable, offices and restaurants in the same tower. The pick for operators who want to live where the work is. Think downtown energy without the drive.
Coral Gables
Historic, canopied streets, A-rated schools, a real village center. This is the Pasadena or San Marino equivalent for families who want standards without the sprawl.
Coconut Grove
Lush, waterfront, marinas and boutiques, actual tree cover. Where I send California families who need green space and water access to feel like themselves.
Wynwood / Edgewater
Newer towers, creative energy, and the neighborhood Miami's tech crowd keeps choosing. Fits the buyer who liked Silver Lake or the Arts District.
Miami Beach & Surfside
Beach living with real price variation between buildings. Strong buyer leverage right now, but building financials matter enormously here — do not shop on view alone.
Fort Lauderdale & Boca Raton
More square footage on the water for the money, plus the corporate campuses pulling north. Serious options if your company is landing in Broward or Palm Beach County.
How to Buy From 2,700 Miles Away
Buying sight-unseen from the West Coast is routine in this migration. I do it with clients constantly. It works when you run the right playbook, and it goes sideways when you don't.
Step 1: Get pre-approved before you book the flight
Well-priced units don't sit, even in a buyer's market. Pre-approval in hand means you can write the same afternoon you tour something you love. Use a lender who knows Miami high-rises — not every loan program works in buildings with high investor ratios or short-term rental activity.
Step 2: Understand that the leverage isn't evenly spread
Miami-Dade condo supply is running above 14 months and condos are averaging roughly 71 days to contract versus 53 for single-family. That reads as a buyer's market, and it is. But some buildings are genuinely soft and some are still competitive, and knowing which is which is the whole job. Read how to actually use the leverage before you start touring.
Step 3: Read the building's financials before you fall in love
This is where California buyers get hurt worst, because HOAs in California rarely behave like ours. Since Florida tightened its condo safety and reserve laws, structural reserve studies and milestone inspections have hit older buildings hard. Special assessments in 1970s and 1980s towers can run tens of thousands of dollars per unit, and more than a thousand Florida buildings currently sit on Fannie Mae's unavailable-financing list. Two units that look identical can carry wildly different ten-year costs. Review reserves, pending assessments, and litigation before you write. I have talked more than one client out of a beautiful unit in a broke building, and I'd do it again.
Step 4: Never skip the inspection
California has seismic retrofits and fire hardening. We have impact windows, saltwater corrosion, roof age, and insurance history. A Florida-licensed inspector isn't optional. It's how you avoid inheriting someone else's deferred maintenance.
A lot of California families want to rent for a year to test the humidity. That's fair and I'll help you do it. But understand the clock: companies are still announcing moves here, and executives routinely buy a personal residence before the announcement goes public. Every month you rent is a month of equity you don't own in a market where demand is being manufactured right now. I regularly set clients up in a short-term furnished rental while we hunt the right purchase. You get the test drive and you keep the leverage.
Establishing Florida Residency the Right Way
The savings are real, but California is aggressive about residency audits, and you have to actually move your life — not just your mailing address. Do it cleanly and the savings are yours to keep:
- Get a Florida driver's license and surrender your California one
- Register to vote in Florida
- Register your vehicles here
- File a Declaration of Domicile with your Florida county clerk
- Update your will, trust, and powers of attorney under Florida law
- Spend more than 183 days a year in Florida — and keep records that prove it
- Move your primary bank, brokerage, doctors, gym, and professional ties south
- File your homestead exemption on your Florida primary residence
If you own a business, hold significant equity, or plan to keep property in California, work with a CPA who handles multi-state moves. California scrutinizes these transitions more than most states do. The savings are big enough to justify doing it precisely, and timing a liquidity event around your residency change is a conversation worth having before you sign anything.
Protecting What You Built on the Way Out
Most relocation advice stops at the closing table. Mine doesn't, because buying the home is only the first pillar. The second is protecting the family. The third is legacy. Here's what I make sure my relocating clients look at:
- Coverage tied to your old employer. If you're leaving a California company, group life coverage can end the day your employment does. A brand-new Miami mortgage is exactly the wrong moment to be uninsured. Mortgage protection means that if something happens to you, the loan gets paid and your family keeps the home instead of listing it in a hurry.
- Liquidity when you buy. Just because you can pay cash for a Miami condo doesn't always mean you should tie up every dollar in one. This matters more than usual in a market with assessment risk — I'd rather you buy strong and keep reserves working than own free and clear with nothing behind you.
- Where the freed-up tax money goes. Households that just erased a 13.3% state bite usually want that money working, not drifting. That's a conversation with a licensed professional about tax-advantaged vehicles. Not a product pitch. A plan.
I've rebuilt my life more than once. From Omaha to New York, to Atlanta, to Los Angeles, and then here. Every one of those moves cost me something and gave me something bigger. The people who come out ahead aren't the ones who moved fastest. They're the ones who moved on purpose — who ran the numbers, bought the right asset, and put protection around it before they needed it.
Deal Alerts
Get South Florida Deal Alerts for Your Move
New listings, neighborhoods, and market openings for your relocation — before the crowd sees them. Plus your Move to South Florida Kit — free, instant download.
Ready to Make the Move?
If you're ready to make the move, I'm ready to help you do it right — the home, the protection, and the plan behind both. Let's build something real.
Frequently Asked Questions
How much do you save on taxes moving from California to Miami?
California's top marginal income tax rate is 13.3%, the highest in the country, and capital gains are taxed as ordinary income. Florida charges zero income tax, zero capital gains tax, and no estate or gift tax. A household paying roughly $45,000 a year in California state tax keeps all of it here. On a $5 million equity event, California's top rate is about $665,000 and Florida's is zero. Your exact numbers depend on income, deductions, and filing status — have a CPA run them.
How many Californians are actually moving to Florida?
The most recent American Community Survey estimates show 36,194 Californians moved to Florida in a single year against 15,988 going the other way — a net gain of about 20,200 people. Among Californians researching a move in 2026, Florida ranks second behind Texas. It's a steady flow rather than a spike, which is why it hasn't fully priced into the condo market yet.
Is now a good time for a California buyer to purchase a Miami condo?
It's one of the better windows in years if you come prepared. Miami-Dade condo supply is running above 14 months — firmly a buyer's market — while luxury and corporate relocation demand keep climbing. Condos average roughly 71 days to contract versus 53 for single-family. That gives a prepared buyer real room on price, closing costs, and concessions. It does not exist in every building.
Should I rent or buy when I move from California to South Florida?
If you're certain about the move, buying sooner locks in today's pricing while the condo market still favors buyers. Renting first is reasonable if you want to test the humidity and the neighborhoods. Many of my clients do both — a short-term furnished rental while we search for the right purchase.
What surprises California buyers most about Miami condos?
The building financials. HOA fees, reserve requirements, and special assessments vary enormously between buildings, and Florida's tightened condo safety and reserve laws widened that gap. Older towers are issuing assessments that can run tens of thousands per unit, and over a thousand Florida buildings currently sit on Fannie Mae's unavailable-financing list. Always review reserves, pending assessments, and litigation before you write an offer.
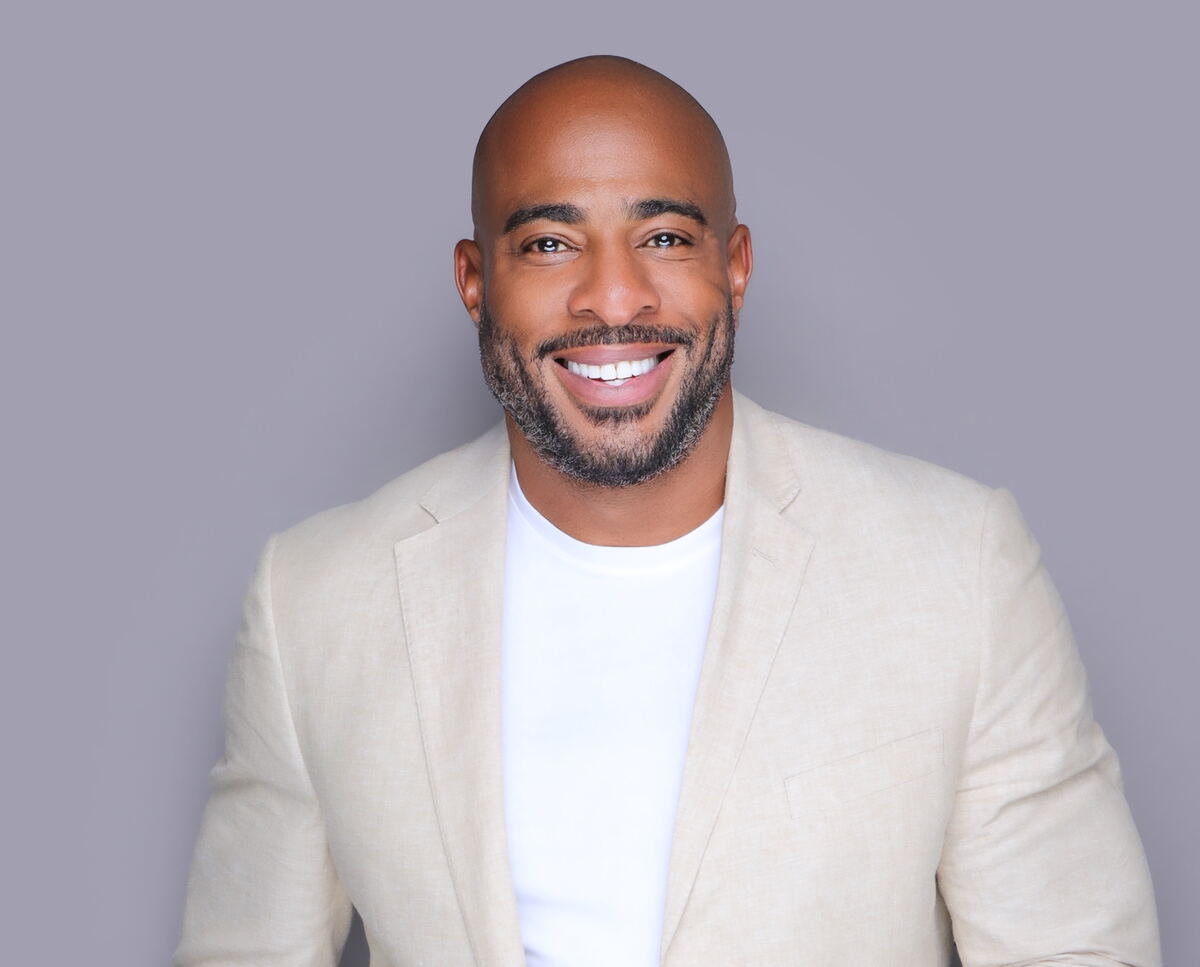
Agu Ukaogo
South Florida Luxury Realtor & Wealth Protection Strategist. Licensed real estate professional and insurance advisor. Helping buyers, investors, and out-of-state transplants navigate South Florida real estate and protect their wealth. HomeWithAgu.com · (786) 417-1897