I've had the same conversation four times in the last two weeks. A client relocating from New York or California, usually with the move penciled in for spring, asks me some version of: "Is there any reason to rush this?"
Up until recently my answer was about the market — condo supply, seller credits, leverage. Now there's a second answer, and it has a hard date on it. If you're planning a move to Florida, the property tax amendment on the November ballot may have just put a price on waiting.
What Amendment 3 Actually Does
Amendment 3 goes before Florida voters on November 3, 2026, and it needs 60% to pass. If it does, it rewrites the homestead exemption — the tax break you get on your primary residence.
Here's the piece most people moving here haven't heard. The ballot language says people who are not Florida residents on December 31, 2026 get the existing exemption when they homestead, and only move up to the larger exemption beginning with their fifth year. Residents as of that date get the bigger number as soon as they homestead a property.
Same house. Same street. Same tax bill for the neighbor who moved in December versus the family who moved in January? No. For four years, it's not the same at all.
Based on the guidance county property appraisers have published, the cutoff is about residency, not closing on a home. Establish genuine Florida residency by December 31 and you'd be eligible for the higher exemption when you do buy and apply for homestead — even if that purchase happens later.
What Waiting Could Cost You
Let's put real numbers on it. The Pinellas County Property Appraiser ran an illustration using a non-school rate of about 12 mills: an extra $100,000 of exemption is worth roughly $1,200 a year, and an extra $200,000 is worth roughly $2,400 a year. Millage varies across Miami-Dade, Broward, and Palm Beach, but that's a fair ballpark.
Now run it for a family that becomes a Florida resident in January 2027 instead of December 2026. They'd sit on the roughly $50,000 new-resident exemption for four years while a December arrival gets the full amount. That's around $8,000 or more in non-school property taxes left on the table — and more if your city's rate is higher or the Legislature pushes the exemption past $250,000, which the amendment explicitly allows it to do.
School taxes don't change — only the first $25,000 stays exempt from those. Save Our Homes, the 3% cap on how fast a homestead's assessed value can rise, stays in place. Portability stays in place. So the amendment stacks on top of the protections that already make Florida homesteading so powerful.
What It Doesn't Change
I'm not going to oversell this. A few honest caveats I give every client:
- It might not pass. Sixty percent is a high bar, and cities, counties, and public safety groups are opposing it.
- Details aren't final. The Legislature still has to write implementing law, and the residency split carries a legal caveat about what the U.S. Constitution permits.
- Second homes don't get it. If this is a vacation condo, the change for you is the non-homestead assessment cap dropping from 10% to 5%. Helpful, but not the same prize.
- Local rates can move. Cities losing revenue may raise millage. The exemption shrinks your taxable value, not the rate.
But here's how I think about it. If you're already moving here in the next six months anyway, establishing residency before December 31 costs you very little. If the amendment fails, you lost nothing. If it passes, you just protected four years of savings. That's asymmetric, and I like asymmetric bets.
How I'd Plan the Move From Here
Get honest about your timeline first. If the move is real and coming within months, talk to your CPA or a tax attorney this week about whether pulling residency forward makes sense for you. Domicile has to be genuine — you actually live here and intend to stay. New York and California both audit people who leave, and I never want a client saving on Florida property taxes while picking a fight with their old state.
Know what residency looks like on paper. Typically that means a Florida driver's license, voter registration, vehicle registration, a Declaration of Domicile filed with the county clerk, and moving your mailing address and tax filings here. Your advisor will tell you what matters most for your situation.
You can rent and still qualify. This is where it ties back to the rent-first-or-buy question. A lease signed before December 31 with a genuine move can establish residency without forcing a rushed purchase. That gives you time to shop a condo market that's still heavy with supply.
Then shop from a position of strength. Miami-Dade condo supply has been running near 12 months, and sellers are funding credits to move units. Buyers have real leverage in the Miami condo market, and the condo turnaround is still working through the system. With the 30-year fixed back above 7% in mid-September, cash and well-prepared buyers are the ones setting terms.
This is also why the corporate relocation wave matters to you. Palantir, D-Wave, GFL Environmental, and a long line of firms before them have been pulling executives and staff here all year. That migration is what keeps South Florida demand durable, and Amendment 3, if it passes, just gave every one of those future transplants a reason to move sooner rather than later.
Buy the Home. Protect the Family.
A lower property tax bill is protection, plain and simple. It's money that stays in your household every year you own the home. But I'll say what I always say: the tax break only matters if the home stays in your family.
When I lost my mother in 2012, shortly after I moved to Los Angeles, I learned how fast a family's plans can change when nobody prepared for the worst day. So when clients relocate, I ask them to fix two things in the same season: their residency and their protection. New state, new home, new job — that's the moment to make sure your coverage fits the life you're building here, not the one you left.
Move with a plan. Buy the honest building. Keep your reserves. Buy the home. Protect the family. Build the legacy.
If you're weighing a move to South Florida and want to map your timeline against this deadline, I'll walk through it with you straight. Call me at (786) 417-1897 or visit HomeWithAgu.com. Let's build something real.
Planning Your Move to South Florida?
Tell me your timeline, where you're coming from, and where you'll be working. I'll show you which neighborhoods fit, where buyers have leverage right now, and how to sequence your move around the residency deadline.
Frequently Asked Questions
What is Florida Amendment 3 and how does it affect people moving to Florida?
Amendment 3 is on Florida's November 3, 2026 ballot and needs 60% of the vote to pass. If approved, it raises the homestead exemption on non-school property taxes to $150,000 in 2027 and $250,000 in 2028, with the Legislature able to push it higher later. People who are Florida residents on December 31, 2026 qualify for the larger exemption once they homestead a property. People who become residents on or after January 1, 2027 start with the existing roughly $50,000 exemption and only move up to the larger amount beginning in their fifth year of homestead.
Do I have to buy a home in Florida by December 31, 2026 to qualify for the larger homestead exemption?
Based on the guidance county property appraisers have published, no. The cutoff is about being a permanent Florida resident by December 31, 2026, not about closing on a home. Someone who establishes genuine residency by that date and buys later would be eligible for the higher exemption when they apply for homestead. Residency has to be real, meaning Florida is your actual domicile, so talk to a tax professional before relying on it, especially if you are leaving a high-tax state that audits departures.
How much could missing the Amendment 3 residency deadline cost a Miami homeowner?
It depends on your assessed value and your local non-school millage rate. As an illustration, at a non-school rate around 12 mills, an extra $100,000 of exemption is worth about $1,200 a year and an extra $200,000 is worth about $2,400 a year. A buyer who becomes a resident in 2027 instead of 2026 could give up roughly $8,000 or more in non-school property tax savings over the first four years, and more if local rates are higher or the exemption is later increased. Actual savings depend on implementing legislation and future millage rates.
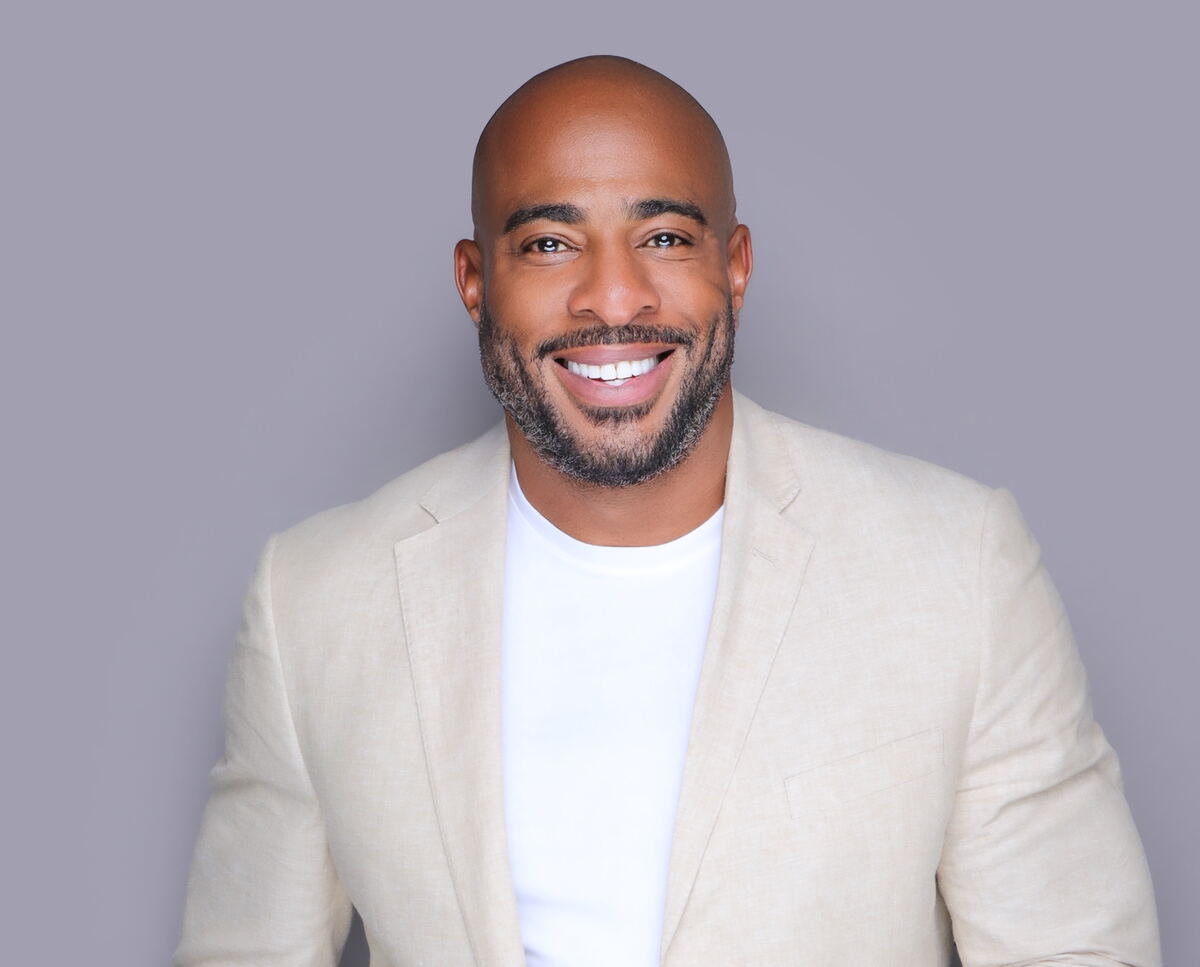
Agu Ukaogo
South Florida Luxury Realtor & Wealth Protection Strategist. FL Real Estate License: SL3588365. Bridges real estate transactions with life insurance and wealth protection that keeps homes in families. HomeWithAgu.com · (786) 417-1897