A buyer sent me a listing last month and said, "It's $60,000 under everything else in the building. Why wouldn't I jump?" I asked him one question: "Have you read the budget?" He hadn't. We read it together that night. The reserve line was nearly empty and the board minutes mentioned a roof.
He didn't buy it. That's the whole lesson of this post: in a buyer's market, the discount is not the deal. The paperwork is.
The Market Gives You Leverage. The Documents Tell You Where.
Miami-Dade's condo and townhome median price was about $417,090 in September 2026, down roughly 1% from a year earlier. Active inventory sat near 11,700 listings, with about 2,000 new ones hitting the market in the month. Prices are flat, supply is deep, and you have room to negotiate. I walk through how to use that room in my buyer's-market leverage playbook.
But a flat countywide median hides a wide spread from building to building. Some towers are well run and fully funded. Others are one bad inspection away from a bill. The documents are how you tell them apart, and I read them before I let a client fall in love with a unit.
Never negotiate price before you've read the building. A 6% discount on a building with a $40,000 assessment coming isn't a discount. It's a down payment on someone else's deferred maintenance.
The 7 Red Flags I Check Before Any Offer
1. A reserve account that doesn't match the repair list
Pull the budget and the structural integrity reserve study. Compare what the study says needs replacing with what the association has actually set aside. A big gap tells you the money will come from owners, either through higher dues or a one-time assessment. I break down how the state's reserve rules changed this in my reserve law buyer guide.
2. Board minutes that keep circling the same problem
Read twelve months of minutes. If the same roof, garage, or plumbing issue shows up meeting after meeting without a vote or a funding plan, the board is stalling. Stalling gets expensive.
3. A milestone inspection with open items
Older buildings must be inspected, and the reports are some of the most honest documents you'll ever see. Ask whether repairs are complete, scheduled, or funded. "Scheduled" with no money behind it is a warning.
4. A special assessment that's pending or likely
Ask directly: is one approved, proposed, or being discussed? Then ask who pays it if it lands after you sign but before you close. I cover how to turn that risk into price and credit in my guide on special assessment leverage.
5. Dues that jumped, or a budget that looks too good
A sharp rise in HOA dues over two years can mean the board is catching up. Dues that haven't moved in five years can mean it isn't. Neither is automatically bad. Both need an explanation. I wrote about what dues really do to your monthly payment in Miami condo HOA fees.
6. Insurance that's thin or about to reprice
Check the master policy, the deductible, and the renewal date. Wind deductibles and renewal swings flow straight to owners through dues. This is where my insurance license earns its keep on a purchase: I read the certificate the way an underwriter does, not the way a listing agent does.
7. Litigation, or a building lenders won't touch
Lawsuits, a high share of investor-owned units, or unpaid dues from many owners can make a building hard to finance. That hurts you twice, today if you need a loan and later when your buyer does. If you're deciding between paying cash and a mortgage here, read my breakdown of cash vs. financing, and see the Fannie Mae condo rules that drive lender approval.
How I Turn a Red Flag Into Leverage
Finding a flag doesn't mean walking away. It means you know something the seller has to price in. Depending on what the documents show, I'll ask for a price reduction that reflects the likely assessment, a seller credit at closing, a longer review window, or the seller's agreement to pay an assessment that's already approved. If the building's story is bad and the seller won't move, we walk. I've walked clients away from deals they loved, and a few of them thanked me a year later.
Here's the part most agents skip: the estoppel certificate. It shows what the unit owes and whether dues are current. Get it, read it, and confirm the closing figures match. Your contract sets how long you have to review the condo documents and when you can cancel, so know that date before you sign, not after.
Buy the Home. Protect the Family. Build the Legacy.
That's how I run every purchase. Buying the home is the easy part. Protecting the family means not signing up for a surprise bill that forces a sale. Building the legacy means owning in a building that will still hold its value when it's time to sell or pass it on. Reserves matter for the same reason savings matter: they're what keeps you in the game when something breaks.
The Miami condo market is handing buyers real negotiating room right now. The buyers who use it well are the ones who read before they offer. If you've got a unit in mind, send me the building and I'll go through the documents with you line by line. Call me at (305) 791-0812 or visit HomeWithAgu.com. Let's build something real.
Deal Alerts
Get South Florida Deal Alerts + Building Intel
New listings, price cuts, and the buildings I'd actually put a client in — sent before the crowd sees them. Plus my Condo Due Diligence Checklist — free, instant download.
Send Me the Building. I'll Read the Documents With You.
Found a Miami condo you like? Send me the address and I'll help you review the budget, reserve study, and board minutes before you write an offer.
Frequently Asked Questions
What documents should I review before buying a Miami condo?
Before you make or finalize an offer on a Miami condo, review the association's current budget, the most recent financial statements, the structural integrity reserve study and milestone inspection reports where the building requires them, the board meeting minutes from the past 12 months, the insurance certificate, and the estoppel certificate showing what the unit owes. Together these show whether the building has funded its reserves, whether major repairs are coming, and whether a special assessment could land on you after closing. Your contract controls how long you have to review them, so confirm that deadline on day one.
What is the biggest red flag in a Miami condo's paperwork?
A building that has not funded its reserves while major work is overdue. Underfunded reserves, deferred maintenance flagged in an inspection or reserve study, and board minutes discussing a future assessment usually point to the same outcome: higher dues or a large one-time bill for owners. It can also make the building hard to finance, which shrinks your pool of future buyers when you sell. I treat that combination as a reason to renegotiate the price or walk away.
Does a buyer's market mean every Miami condo is a deal?
No. Countywide condo prices are roughly flat to slightly down, but the spread between buildings is wide. A well-run building with healthy reserves and a smaller discount can be a better purchase than a cheaper tower facing deferred repairs. Leverage is real, but you use it building by building, and the documents tell you where it is and where it is a trap.
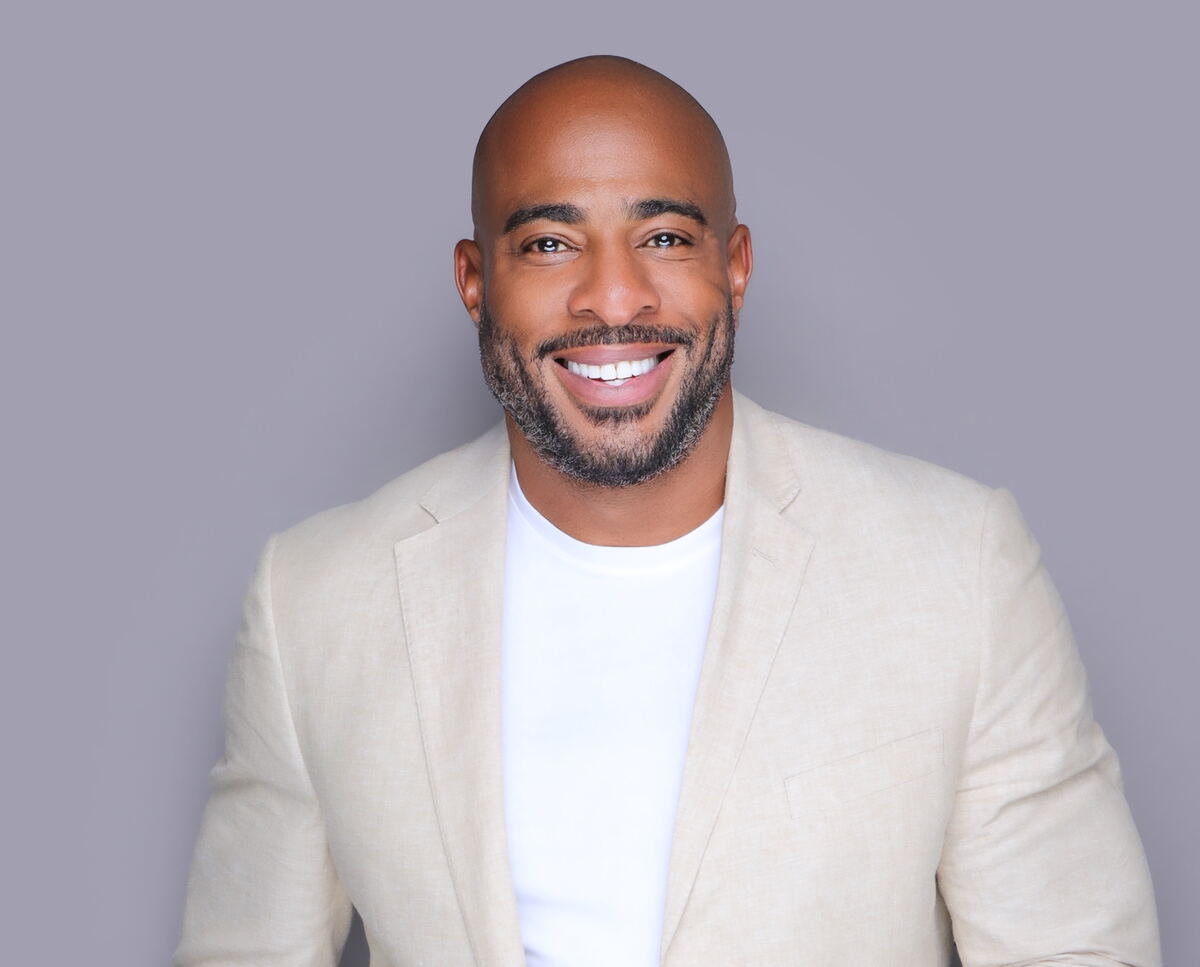
Agu Ukaogo
South Florida Luxury Realtor & Wealth Protection Strategist. FL Real Estate License SL3588365 | Insurance NPN 22138920. One of the few advisors in Miami licensed in both real estate and insurance. HomeWithAgu.com · (305) 791-0812