A couple from the Denver area sat across from me last spring and said, "We love the mountains, we're done with the winters, and we've never owned anything near salt water. What are we missing?" It was the right question. Almost everyone leaving Colorado for Miami is focused on the sunshine. The ones who buy well are focused on what changes underneath it.
I've moved my whole life, from Omaha to Los Angeles and beyond, and I learned that a new city rewrites your daily routine before it touches your bank account. Here's what I walk Colorado buyers through before we tour a single home.
The Tax Swap Is Real. Read the Fine Print.
Florida has no state income tax on wages. Colorado does, so for a household with a strong income the difference can be meaningful. I never wave that away. But I also never let it be the whole story, because Florida makes up some of that cost elsewhere: homeowners insurance, flood coverage, condo association dues, and sales taxes that you'll feel on everyday purchases. If you're building a budget, compare your all-in monthly cost of ownership in both states. I show clients how to run that math in cash vs. financing on a Miami condo.
Don't buy Miami because of the tax line. Buy it because the all-in monthly number works for your life, then let the tax savings be the cushion.
Altitude to Sea Level: Your House Has a New Enemy
In Colorado, your home's biggest threats were hail, snow load, and wildfire smoke. In South Florida it's water and wind. Humidity, storm surge, and flood zones are part of the buying conversation here, and they decide what insurance costs. I've seen buyers fall in love with a home and then discover the flood zone and wind coverage changed the monthly payment by hundreds of dollars.
That's why I carry both a real estate license and an insurance license. Before you write an offer, I want a quote in hand, not a guess. Buy the home. Protect the family. Build the legacy. Those are in that order for a reason, and the protection part has to be priced before closing.
Questions I run through with Colorado buyers
- Have you felt a South Florida August, and are you comfortable with the humidity and the storm season that comes with it?
- Which flood zone is the property in, and what do wind, flood, and condo master policies cost?
- Do you want lock-and-leave convenience, or do you need a yard, a garage, and room for the gear you're bringing?
- Will you live here full time, or split the year between Miami and somewhere cooler?
Condo or House? Right Now, the Condo Side Has Leverage
Many Colorado buyers arrive wanting a house, because that's what they sold. Then they see the cost of insuring and maintaining one in Miami and look harder at condos. South Florida condo supply has given buyers room to negotiate on price, credits, and closing dates in many buildings. I break that down in the Miami condo buyer's market playbook and show where the market is heading in the South Florida condo market turnaround.
But a condo is a building before it's a unit. Reserves, pending special assessments, rental rules, and master insurance renewals matter more than the granite in the kitchen. I never let a client skip that homework.
The Job Market Is Following You
One reason I'm bullish on people relocating here is that employers keep coming. Companies are expanding their South Florida footprints, and that brings executives, advisors, and families who need to live somewhere. I covered the bigger picture in why corporate relocations keep driving luxury demand. If your employer is also moving you, read my timeline for buying a home when your company relocates you.
My Playbook for Moving From Colorado to Miami
- Rent or visit first. Spend real time in the neighborhoods you like, in summer if you can. I explain the tradeoff in rent first or buy.
- Get insurance quotes before offers. Wind, flood, and condo coverage change the real price of a home.
- Pick the building or street before the unit. Check reserves, assessments, and flood history.
- Negotiate beyond price. Credits, repairs, and closing dates are often easier wins when supply is deep.
- Plan for the long game. Buy something that still makes sense to the next buyer when you're ready to sell.
If you're buying from out of state, my remote buyer playbook covers touring and closing from a distance. The couple from Denver bought a condo in a building we vetted together, with insurance priced before they signed. Last I heard, they'd stopped checking the weather app for snow.
If you're ready to make the move, I'm ready to help you do it right. Call me at (305) 791-0812 or visit HomeWithAgu.com. Let's build something real.
Deal Alerts
Get South Florida Deal Alerts + Building Intel
New listings, price cuts, and the buildings I'd actually put a client in — sent before the crowd sees them. Plus my Condo Due Diligence Checklist — free, instant download.
Leaving Colorado for Miami?
Tell me your budget and timeline and I'll map out neighborhoods, building red flags, and the true all-in monthly cost, insurance included.
Frequently Asked Questions
Is Miami cheaper than Colorado for homeowners?
Florida has no state income tax, which is a real swing from Colorado's flat income tax. But insurance, condo fees, and flood coverage can eat into that savings. I tell clients to compare the full monthly cost of owning, not just the tax line.
Should a Colorado buyer purchase a Miami condo or a house?
Condos give you the lock-and-leave lifestyle and, right now, plenty of inventory to negotiate with. A house gives you more space and control over the roof and insurance. Whichever you choose, review the building's reserves, assessments, and insurance before you offer.
Do I need to visit Miami before buying from Colorado?
I'd visit at least once, ideally in summer, so you feel the heat and humidity and see the building in person. If you truly can't, I walk clients through live video tours, inspection reports, and remote closings, but a first visit saves a lot of regret.
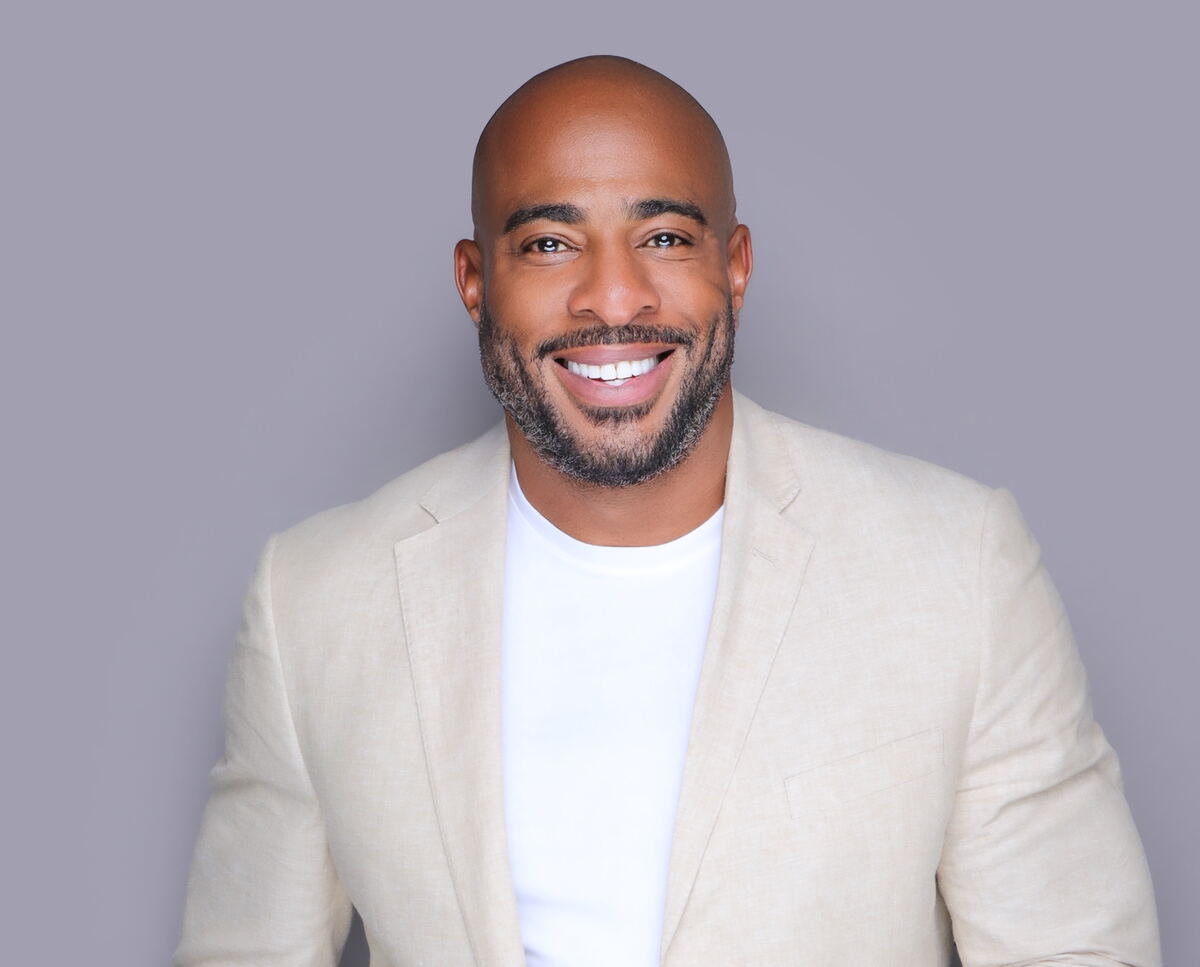
Agu Ukaogo
South Florida Luxury Realtor & Wealth Protection Strategist. FL Real Estate License SL3588365 | Insurance NPN 22138920. One of the few advisors in Miami licensed in both real estate and insurance. HomeWithAgu.com · (305) 791-0812